3 Singaporean Families on Buying Their HDB Resale Flat
Everyone has a BTO-versus-resale debate at some point, usually over kopi at the hawker centre while scrolling PropertyGuru. But numbers on a listing page don't tell you what it's actually like to fork out $30,000 cash-over-valuation or discover your "minor renovation" budget has ballooned by $15,000. So we spoke to three composite Singaporean households — based on common patterns we see — about their actual HDB resale journeys, down to the dollar. Here's what you need to know before you sign that Option to Purchase.
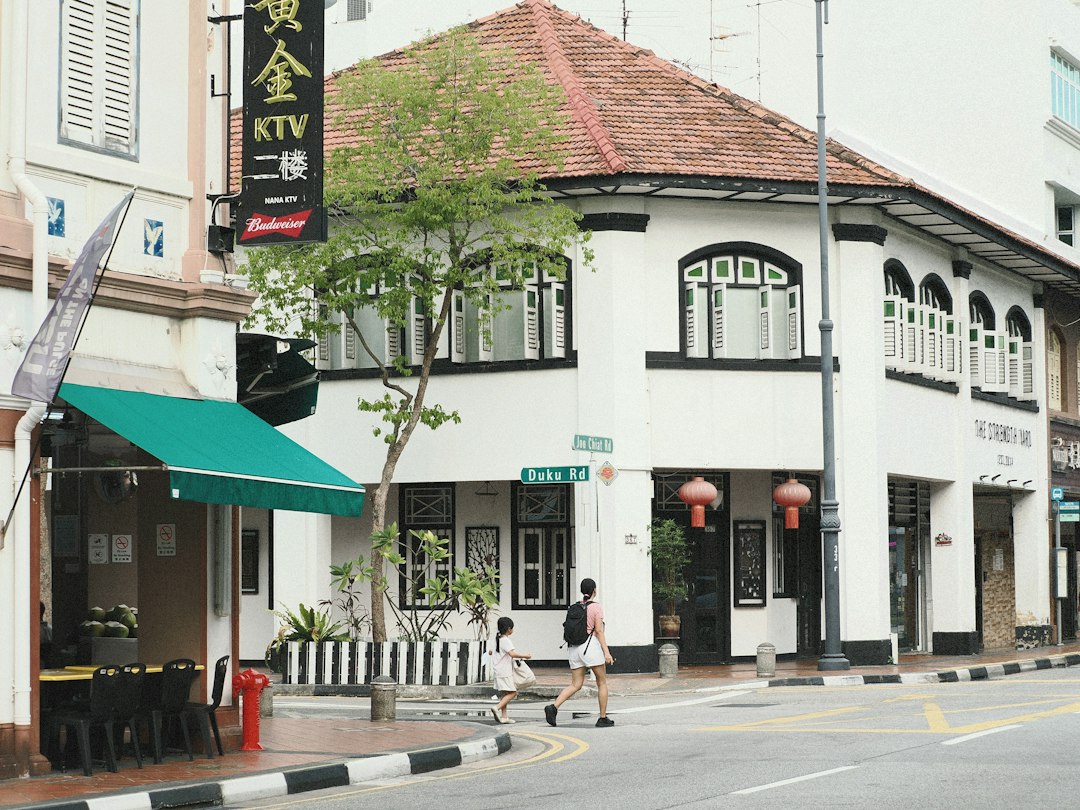
Case Study 1: The Young Couple Who Rushed Into Punggol
Wei Jie (29, engineer) and Hui Min (28, teacher) got married in 2023 and didn't want to wait 4 years for a BTO. They had $120,000 in combined CPF and cash savings and were renting a room in Sengkang while house-hunting. After six months of viewings, they settled on a 4-room resale flat in Punggol, near Waterway Point, with 88 years left on the lease.
The flat was listed at $560,000. After some back-and-forth, they agreed on $548,000 — but the HDB valuation came in at $530,000, meaning an $18,000 Cash Over Valuation (COV) they had to pay entirely in cash, upfront, no CPF or loan allowed.
| Item | Cost (SGD) |
|---|---|
| Resale price | $548,000 |
| COV (cash only) | $18,000 |
| Resale levy | $0 (first-timers) |
| BSD (Buyer's Stamp Duty) | $9,900 |
| Legal fees (HDB conveyancing) | $500 (used HDB's own service) |
| Renovation (minor touch-up) | $22,000 |
| Total upfront cash outlay | ~$38,000 |
Their big lesson? The COV nearly wiped out their emergency fund. "We didn't realise COV had to be 100% cash," is the kind of regret many first-timers echo — it's not something your CPF can touch. Wei Jie and Hui Min now tell friends to keep at least $20,000 cash buffer separate from the purchase budget, specifically earmarked for COV and incidental costs like fire insurance and conservancy charge arrears clearance.
What They'd Do Differently
- Get an HDB valuation estimate done earlier in the process, not after falling in love with a flat
- Negotiate harder when the flat has an awkward layout (theirs had a long, narrow kitchen)
- Budget renovation separately — don't let it eat into the COV reserve
Case Study 2: The Multi-Generational Family in Toa Payoh
The Rajendran family — parents in their mid-50s, plus their 32-year-old son and his wife — pooled resources to buy a 5-room resale flat in Toa Payoh Lorong 1, close to the MRT and the wet market, so grandparents could help with childcare. This was a classic multi-generation move, common in heartland estates where three incomes can chase one flat.
The flat, built in 1985, had 41 years left on the lease — a key consideration since the son was only 32 and CPF usage rules kick in differently when lease-plus-age calculations come into play (CPF usage is capped if the remaining lease can't cover the youngest buyer until age 95).
| Item | Cost (SGD) |
|---|---|
| Resale price | $680,000 |
| COV | $5,000 (older flat, lower demand) |
| BSD | $14,100 |
| Renovation (full overhaul incl. rewiring) | $68,000 |
| New aircon + kitchen appliances | $9,500 |
| Total project cost | ~$776,000 |
Because of the older lease, CPF usage for the son's share was restricted, so they had to top up more cash than expected — about $45,000 extra cash on top of their CPF OA balances. The family's takeaway: older flats near MRT stations in mature estates like Toa Payoh or Ang Mo Kio come with hidden CPF/loan restrictions that younger buyers often miss. They strongly recommend running the numbers through HDB's resale eligibility and CPF usage calculators before making an offer, not after.
Renovation also overshot because the 41-year-old flat needed full rewiring and replumbing — something a pre-purchase inspection would have flagged. If you're eyeing an older unit, it pays to find HDB Resale providers who also offer inspection add-ons before committing.
Case Study 3: The Single Buyer Who Went Budget in Woodlands
Farhan, 38, a single first-timer under the Single Singapore Citizen Scheme, bought a 3-room resale flat in Woodlands near Causeway Point. His budget was tight — about $280,000 total — so he deliberately avoided mature, popular estates and looked at older 3-room units further from the MRT.
| Item | Cost (SGD) |
|---|---|
| Resale price | $268,000 |
| COV | $0 (negotiated at valuation) |
| BSD | $2,520 |
| Legal fees | $500 |
| Renovation (budget, reused existing flooring) | $12,000 |
| Total cash + CPF outlay | ~$283,000 |
Farhan's strategy was patience — he viewed 15 flats over 8 months and specifically targeted sellers who had already bought their next home and needed to move fast, giving him leverage to negotiate COV down to zero. His lesson for other single buyers: don't chase the "hot" estates everyone's talking about on forums. A 15-minute bus ride to the MRT saved him close to $60,000 compared to similar units nearer Woodlands MRT itself.
Shared Lessons Across All Three Stories
- COV is always cash, always upfront. Whether it's $0 or $18,000, never assume CPF or your home loan will cover it.
- Lease decay isn't just a resale-value issue — it affects what you can borrow today. Younger buyers eyeing older flats in Toa Payoh, Bedok, or Ang Mo Kio should check CPF usage limits before falling in love with a unit.
- Renovation budgets blow up on older flats. Rewiring, replumbing and hacking unauthorised structures can add $20,000–$40,000 that first-time buyers rarely plan for.
- Location trade-offs can save tens of thousands. A slightly longer walk or bus ride to the MRT, or an older estate, consistently meant lower COV and purchase prices across all three cases.
- Patience pays off financially. Farhan's 8-month search saved him significantly more than rushing in — though the Punggol couple's experience shows waiting too long in a hot market can also mean prices rise against you.
The Bottom Line
There's no one "right" way to buy an HDB resale flat — your family size, lease priorities, and cash reserves will shape the decision differently, like these three households show. But across every story, the pattern holds: COV eats your cash savings first, older leases restrict your CPF and loan options, and renovation on old units costs more than Pinterest boards suggest. Do your valuation checks early, and build in a buffer of at least 10-15% above your expected total cost.
Ready to start your own resale journey? Get free quotes from verified providers on KakiList for everything from conveyancing to renovation, so you don't end up blowing your COV budget on surprises.
Need help finding the right provider?
Get free, no-obligation quotes from verified hdb resale providers in Singapore.
Get Free Quotes →